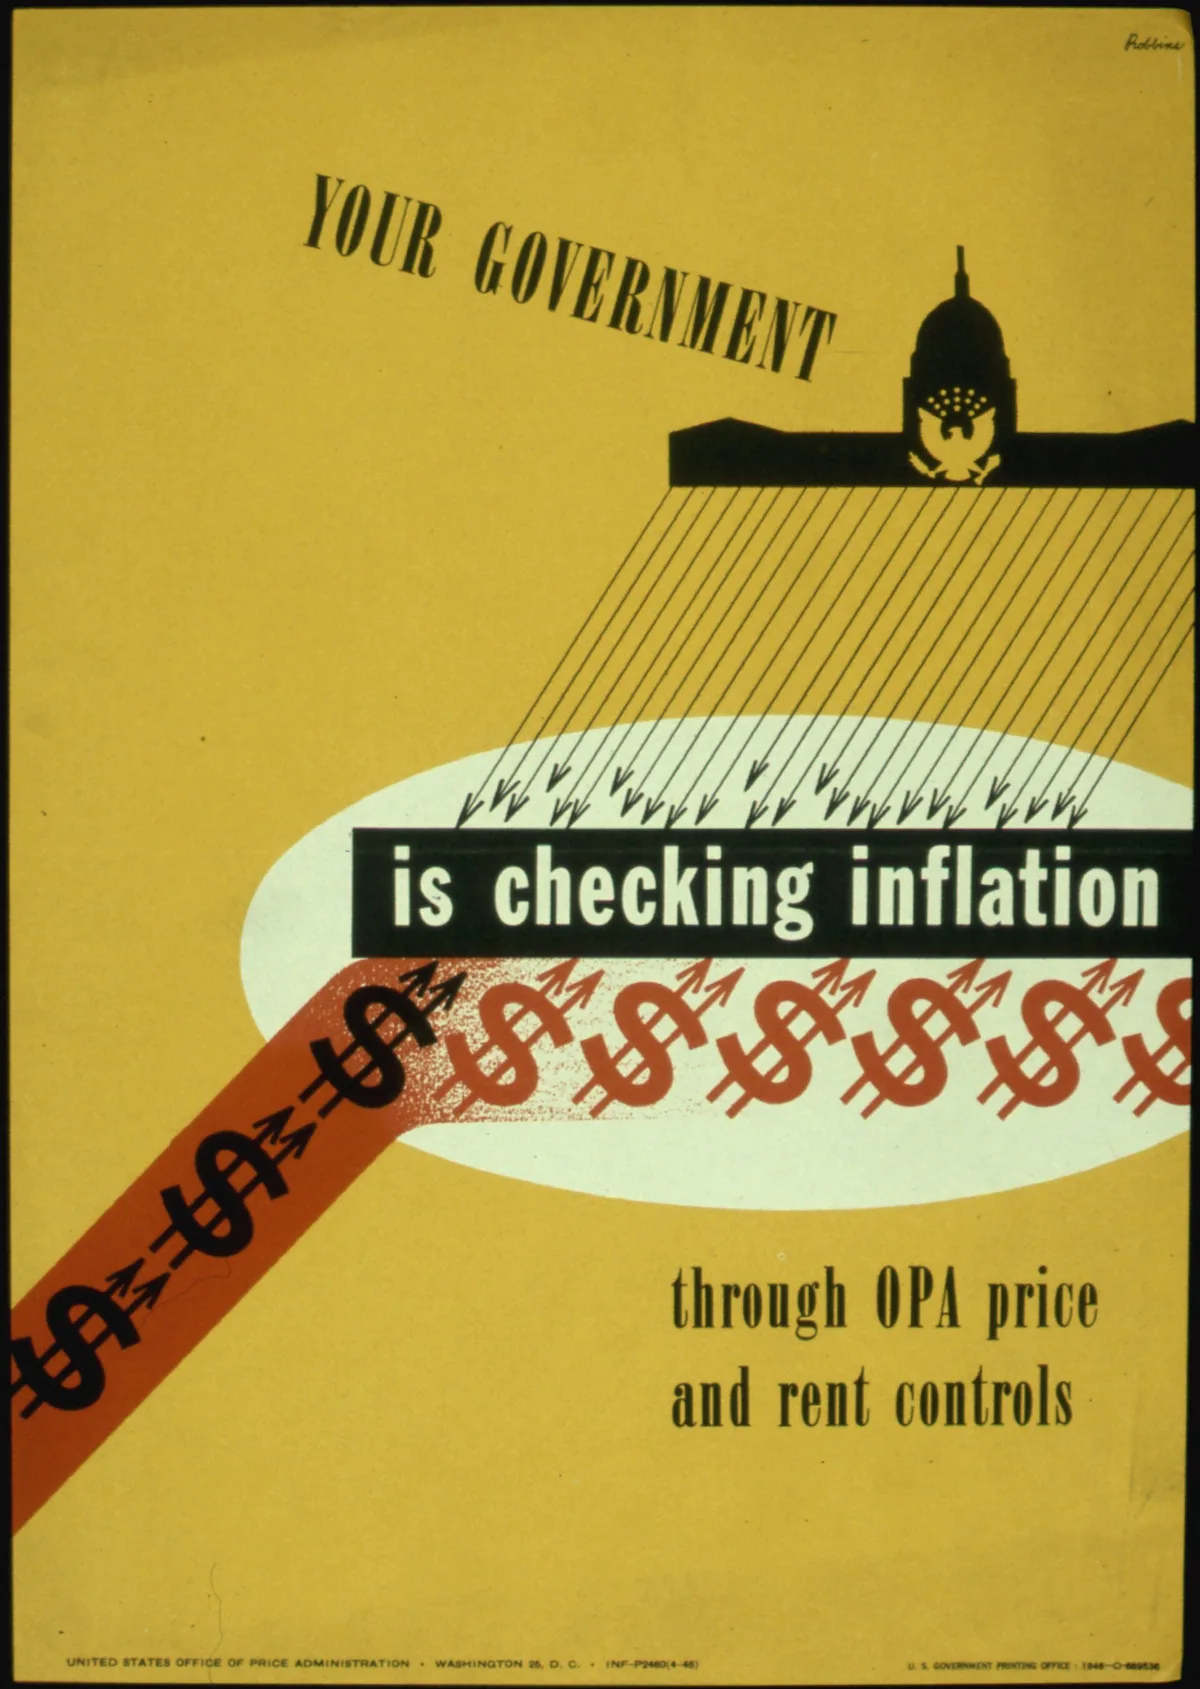
Inflation is a broad, continued rise in the prices of most goods and services, which means each dollar buys less than it did before. The most recent U.S. figure is 3.7% for the 12 months ending September 2026, up from 3.4% in August, per Labor Department data released October 14, 2026.
That number matters for one reason: it is the speed at which your savings and your paycheck lose ground. A 3.7% rate does not feel dramatic month to month. Over a few years, it decides whether a raise is a raise.
This guide explains what inflation actually is, what causes it, how the government measures it, and what it means for a household budget. No jargon, no predictions.
What counts as inflation, and what does not?
Inflation is not every price increase. The Federal Reserve Bank of Cleveland puts the distinction plainly: inflation happens when the prices of many things we buy rise at the same time and then keep rising. One item getting dearer is just a price change.
Oranges can spike after a frost in Florida. Parking can cost more on game day. Neither is inflation. Those prices tend to fall back once supply and demand return to normal, and they involve single items, not the broad basket of goods and services households actually buy.
The opposite of inflation is deflation, a general fall in prices. That sounds pleasant and usually is not. Falling prices push people to delay purchases, which cuts business revenue, which cuts jobs. Most economists prefer a low, steady rate of inflation over either extreme, because it gives the labor market room to adjust and keeps central banks able to respond to a downturn.
What causes prices across the economy to rise?
Economists group the drivers into a few repeat offenders. Changes in the money supply. Sudden jumps in demand for goods and services, sometimes triggered by fiscal or monetary policy. Sudden drops in available supply, such as an energy crisis. Big cuts in central bank interest rates. And expectations: if people believe prices will rise, workers demand higher wages and firms raise prices ahead of it, which can make the belief self-fulfilling.
Supply shocks and demand shocks are the two you hear about most. A supply shock means stuff gets harder to make or move, so it gets more expensive. A demand shock means more money chases the same goods. Both end in the same place: higher prices across many categories at once.
One clarification worth keeping. Inflation refers to the general trend, not any specific price. If shoppers shift from tomatoes to cucumbers, cucumbers get dearer and tomatoes cheaper. That is a change in tastes, not inflation. The term concerns the value of money itself.
How is inflation measured?
The standard yardstick is the Consumer Price Index, or CPI, published monthly by the Labor Department's Bureau of Labor Statistics. Government statisticians collect prices for thousands of goods and services, combine them into an index, and report the change over time. When the index is higher than a year ago, prices are higher on average, and that is inflation.
The annual rate is simple arithmetic. Take this September's CPI, subtract last September's CPI, divide by last September's figure, and multiply by 100. That 12-month change is the headline number in every monthly report.
The annual inflation rate data assembled from BLS figures show how wide the swings can be. The 12-month rate ran 9.1% in June 2022, the peak of the recent surge, and 1.4% in 2020. For calendar year 2025 the December-to-December rate was 2.7%. Monthly moves are smaller and noisier: September 2026 prices rose 0.6% from August, seasonally adjusted.
One caution when reading the monthly release: some figures are seasonally adjusted and some are not, and the headline annual rate uses the unadjusted series. Our guide on how to read a CPI report without panicking walks through the differences.
What does inflation mean for your money?
Three things, and none of them subtle.
First, purchasing power. At 3.7% inflation, a fixed $1,000 buys roughly 3.7% less over a year. Cash sitting idle loses value at exactly the inflation rate. That is the quiet tax nobody votes on.
Second, wages. What matters is not your paycheck but your paycheck minus inflation. If prices rise faster than pay, real wages fall, even if the number on the stub grows. The wages-versus-prices math is where most households feel inflation first. We covered a connected angle in Wages vs prices: the real cost-of-living math.
Third, specific categories can outrun the average. Per the Bureau of Labor Statistics, from September 2025 to September 2026 gasoline prices rose 34.2%, fuel oil rose 74.2%, and airline fares rose 22.4%, while all-items prices rose 3.7%. Someone who drives to work experienced a very different year than the headline number suggests. The all-items figure is an average; your personal inflation rate depends on your own basket.
What this means for planning a budget
The practical takeaway is structural, not a tip list. Inflation rewards assets whose prices tend to rise with the economy and penalizes idle cash and fixed payments. It makes long-term contracts, like a fixed-rate loan, cheaper in real terms over time. It makes a salary that never changes a real pay cut every year.
Households cannot control the rate. What they control is exposure: how much of their money sits in instruments that track inflation, how often income is renegotiated, and whether big purchases are timed against borrowing costs. None of that requires forecasting. It requires knowing which side of the inflation ledger each piece of your finances sits on.
For the broader picture of how these releases fit together, the economy news section tracks each monthly data drop with the same method-first approach.
What the evidence establishes, and what it does not
Established: inflation is a broad, sustained price rise measured by indexes like CPI; it ran 3.7% for the year ending September 2026; energy prices rose far faster than the average over that period. Established: most economists favor low, steady inflation, and central banks are the institutions tasked with keeping it there.
Not established by the data: where the rate goes next, and which cause dominates any given month. The next CPI update is scheduled for November 10 at 8:30 a.m. ET, covering the 12 months ending October. Read the release, not the reaction.